
The traditional asset class demarcations between real estate, private equity and infrastructure are beginning to blur as institutional allocators adopt a total portfolio approach (TPA) to evaluate opportunities across private markets.
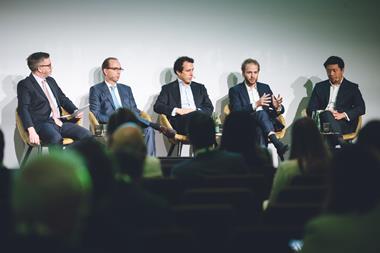
In a discussion on asset allocation trends at the IPE Real Assets Infrastructure & Natural Capital Global Conference & Awards 2026 in Munich, panel members discussed how flexible capital allocation frameworks and cross-asset class competition are shifting how institutional capital is deployed.
Katya Romashkan, portfolio manager of infrastructure at Aware Super, explained how the Australian superannuation fund has implemented this model across its private markets division. While Aware Super maintains dedicated private equity, property and infrastructure teams out of its London office, the fund has introduced a flexible pot of capital that sits outside standard asset class buckets.
“All three of these [asset classes] could compete for the capital,” Romashkan said, with Aware Super “judging deals from a risk-return perspective to see where that small pot of capital can go to which asset class”.
Such approaches allow institutional investors to navigate grey areas between asset classes where traditional definitions break down. As Romashkan said, assets such as motor service areas or core data centres raise structural questions around whether they represent property, infrastructure or private equity-style value-add plays. Under a TPA framework, bringing diverse deals to a single pool of capital enables allocators to “pick and choose to make sure you got the best risk-adjusted return”.
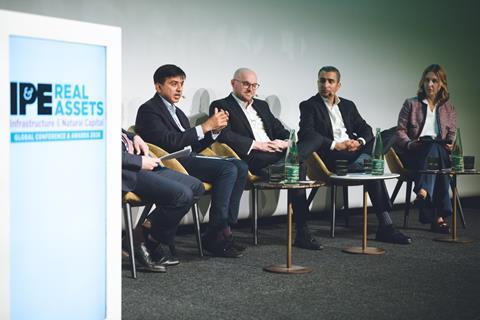
Likewise, Ahmed Mubashir, managing director and head of infrastructure EMEA & India at Canadian pension fund AIMCo, said several allocators are moving to merge real estate and infrastructure functions to give themselves greater flexibility when deploying real assets allocations.
However, panellists also said that evaluating opportunities across asset classes requires heightened discipline, particularly as market participants expand definitions into higher-risk segments.
Anish Butani, managing director of private markets at investment consultancy bfinance, said that more investors are examining infrastructure from a TPA perspective, but cautioned against unrewarded scope creep as managers pursue growth-oriented megatrends like energy transition and digitalisation.
Fiduciary discipline vs local investment pressures
As governments globally seek to channel pension capital into domestic infrastructure, institutional allocators maintain that risk-adjusted returns must take absolute precedence over national economic development mandates.
Romashkan said that, while tax incentives create a natural economic preference for Australian schemes to invest domestically, intense competition forces Aware Super to screen global markets objectively. The fund conducts rigorous screens across deep European markets, including Germany, France, the UK, the Netherlands and the Nordics, to keep its five-person London team targeted on the best opportunities.
Canadian and UK allocators operate under a similar mandate. Mubashir said: “AIMCo doesn’t have an economic development mandate. Again, we have to chase the best risk-adjusted return and see what’s the best for the clients.” While 40% of AIMCo’s total assets remain in Canada, global infrastructure allocation is driven purely by commercial merit.
From a UK perspective, Alex Leonard, head of infrastructure and timberland at the Pension Protection Fund, acknowledged that a home-market tilt helps manage currency risk, but warned against policy-driven misallocation.
Addressing efforts like the Mansion House Compact and local government pension scheme pooling aimed at unlocking domestic capital, Leonard said: “I don’t think you help your home market by doing uneconomic investments. I think you help your home market by keeping your investment discipline.”
Comparing local allocation pressures to potential capital misplacement, Butani said that core financial objectives must not be superseded by political goals. Warning against unrewarded domestic mandates, he added that “investing locally shouldn’t come at the cost of returns,” adding that governments would ultimately “have to pick up the tab” if pensioner returns fall short.
To read the latest IPE Real Assets magazine click here.