
Invesco Real Estate has seen credit surge to account for 50% of its European deal volume this year, up from 25% last year, as institutional limited partners (LPs) prioritise high-yielding, durable income over traditional equity, European head Andy Rofe and fund management lead Kevin Grundy revealed at EXPO Real.
Supported by new separate accounts worth up to €400m raised in the past three months, the manager expects debt allocations to continue expanding alongside its €500m credit fund.
Speaking to IPE Real Assets at the event in Munich, Andy Rofe, managing director, head of Europe and CIO, and Kevin Grundy, managing director, fund management Europe, outlined how the firm is managing capital flows at a time when investors are assessing the ramificatons of interest rates on pricing.
“It’s a mix, really,” said Grundy regarding LP demand. “Credit has been very active, about double what we did the previous year, but equity strategies are still active as well. In terms of risk profiles, it’s leaning a bit more toward value-add at the moment.”
“It’s a really interesting market now because the real estate itself looks good; it’s the capital markets that are disrupted,” Grundy explained. “We’re at a period right now where people are digesting what interest-rate movements mean for pricing. But if you look at tenant demand, occupational demand is strong, and there is rental growth across a number of sectors. The other thing you often look for is constraints in supply, and you’ve got that as well because construction costs have risen so much. So it’s really a nice time to be looking to invest.”
Broad institutional capital across Europe continues to gravitate toward prime, core assets, but Invesco is directing its deployment toward income durability rather than simple prime status.
“I think the broader market is gravitating toward more prime assets,” Grundy said. “But for us, we are focused on income. That is really our story – where can we find durable income? It’s a mix of what we call inelastic income, which is rock-solid and always going to be there, and what we call flexible income, which is essentially income where you can reprice in real time to take advantage of inflationary pressures. A lot of that is in the residential or living sector.”
On the question of whether distress is surfacing across European markets or whether senior lenders are continuing to extend existing loans, Grundy sees a middle ground. “It’s somewhere in the middle. It’s not flat-out distress, but we are beginning to see more motivation from sellers,” he said. “When things shifted a couple of years ago in 2023, it wasn’t deals being done directly with banks, but people coming to the table to try and find a structural solution.”
Geographic value and portfolio liquidity
Across continental markets, relative pricing dynamics are shifting as liquidity unfreezes at varying speeds. According to Rofe, no single country holds a definitive liquidity advantage.
“I don’t think there is any distinct country that necessarily has more liquidity than others,” Rofe said. “A number of investors are looking domestically depending on where they come from, while others are happy with cross-border investment and are focused on where you can get the best pricing points, the most durable income, and where there is the most liquidity.”
“We are seeing opportunities across the board,” Rofe added. “What we are seeing are some pricing shifts that might look potentially more attractive over the next three to six months, across both prime and secondary assets. So it’s a watching brief. If you’ve got equity in this market, it’s a pretty attractive place to look at potential deals. But we are in a shifting market, so the pricing point today is not necessarily what it’s going to be in three to six months.”
Managing portfolio liquidity and redemption queues in open-ended vehicles has also required deliberate asset management. “We’ve been managing that pretty successfully,” Rofe said. “There are different reasons why investors are either reallocating money or putting money back into strategies. Some are coming out of pooled funds and putting their money into separate accounts where they can get more control and go down a sector-specific route.”
“Earlier in July, we sold a very large asset in Paris for about €800m,” Rofe noted. “That was the largest single-asset sale in Europe for four years. That deal allowed for a repositioning of the portfolio, so the portfolio composition is exactly what people want to invest in today – overweight logistics, overweight living, underweight offices – while also providing liquidity for redeeming investors if they want to reallocate to different strategies.”
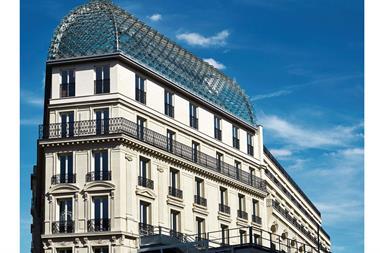
Invesco had held the 45,000sqm Capital 8 office complex in Paris’s 8th arrondissement since late 2018, when it acquired the property from Unibail-Rodamco-Westfield for €789m.
As infrastructure allocators target data centres, Invesco approaches the asset class through a specific real estate lens tied directly to logistics fallback options. “We invest in a very specific part of that spectrum, not the full build-out of data centres, which is a multi-billion-euro investment,” Grundy said.
“What we like, and what we feel is closest to real estate, is the beginning of the journey: putting together the pieces that allow for the creation of a data centre. That means securing the land, planning permission and power. Where it overlaps heavily with real estate is finding sites that have a viable fallback use for traditional logistics, and then working up the potential for a data centre. That way, you can always fall back on the logistics asset.”
“It’s a subset of our logistics strategy, primarily because we look for sites that have alternative logistics uses,” Grundy added. “It is a different animal from traditional logistics, but because the sites have a lot in common, location, power requirements, they overlap. However, we treat it as a distinct asset class.”
The rapid expansion of credit within Invesco’s European business reflects a broader shift among European investors following years of investor education. “In Europe, there has been very strong demand, we’re seeing stronger capital flows into credit at the moment than into equity,” Rofe stated.
“Again, that’s driven by income. You’re getting a total return of between 7% and 8%, with 90% of that generated through income. We approach it from a property-first perspective – we work with expert teams around Europe to ensure that if anything ever goes wrong with a debt investment and you end up owning the asset, you are extremely comfortable owning it.”
Rofe pointed out that integrating debt and equity sourcing gives the firm a distinct approach. “Most of our competitors keep credit and equity as distinct animals, whereas we combine them,” he said. “Our transaction teams around Europe source both equity and debt deals, underwriting the underlying real estate fundamentals, while the credit team determines the appropriate debt sizing and structure for investors.”
Currently, Invesco’s European assets under management remain weighted toward equity at roughly 80% versus 20% debt, but deployment figures point to a changing balance. “In terms of capital deployment this year, about 50% will be in credit and 50% in equity,” Rofe said.
“I expect next year to be broadly similar based on available capital to invest. So the proportion of credit will continue to increase. The commingled fund has about €500m in equity at the moment and is growing… We created two new separate accounts in the last three months that can invest in their own right and alongside the fund. Collectively, those represent roughly €300m to €400m of equity.”
To read the latest IPE Real Assets magazine click here