Realty Income is preparing to expand into European data centres as it seeks to replicate its growing US exposure to the sector, with Frankfurt, London, Paris and Barcelona among the markets in its sights, CEO Sumit Roy has told IPE Real Assets.
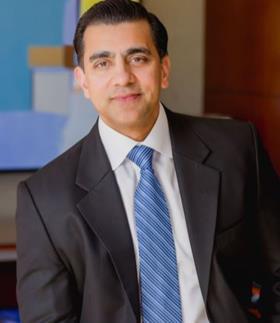
The US-based net-lease giant, which has around $90bn (€78.1bn) of assets globally and approximately $18bn, or 20%, invested in Europe, is looking to build its data centre portfolio alongside its established retail and logistics strategies as it seeks to capitalise on what CEO Sumit Roy describes as a “once-in-a-generation opportunity” driven by demand for digital infrastructure.
“We hope that we start to add data centres to that mix of passive classes,” Roy told IPE Real Assets. “The buildout of data centres here in Europe is slightly behind the US but it’s going to happen. It’s a matter of time.”
Realty Income has already made two data centre investments, including a first transaction with Digital around three years ago, followed by a recently announced transaction of around $6bn with Cloud Capital in Northern Virginia. Roy said the company is in discussions with multiple developers and intends to build a pipeline rather than rely on a single development partner.
The strategy is tightly focused. Realty Income will target single-tenant facilities on long-duration leases with 2-3% annual growth, rather than operationally intensive collocation or multi-tenant facilities. This strategy would allow it to retain the historically defensive characteristics of its net-lease investment strategy.
“That fits our mould of net lease,” Roy said. “That’s the only area.”
The company is targeting established European data centre markets including Frankfurt, London and Paris, while Barcelona is emerging as another market of interest.
Realty Income expects to work with multiple developers, allowing it to select individual assets and markets according to its preferred exposure to location, development and tenant credit.
“We can work with any of them,” Roy said. “We don’t have a single relationship.”
The expansion comes as Realty Income sees stronger risk-adjusted investment opportunities in Europe than in the US, outside data centres, with spreads remaining attractive and competition lower.
When asked whether European investment spreads remained attractive and the market less competitive than the US, Roy said that it is “very true”. “We feel that our cost of capital, our balance sheets, the fact that the market is very fragmented, for all these reasons we feel that an institution like ours can help consolidate the market.”
He attributed the relative lack of competition partly to the higher cost of debt, which has put pressure on leveraged private investors, and to the fragmented nature of European real estate. The company estimates the European real estate market at around $8trn, much of it held by non-institutional owners.
The strategy received a major boost this week with the announcement of a euro-denominated joint venture with KKR, which saw the private equity giant commit €528m for a 49% stake in a seed portfolio of 54 European net-lease assets contributed by Realty Income.
Realty Income has used its scale and access to capital to establish a foothold across the region. Its European strategy includes retail, logistics and industrial assets, with the company continuing to see opportunities in Spain, Italy and Poland for retail, while targeting Poland, Germany, the Netherlands, Italy and Portugal for logistics.
The UK remains its most mature European market. Realty Income entered in 2019 through a more than £429m (€501m) sale-leaseback with Sainsbury’s and has since expanded its strategy across retail, logistics and data centres.
Roy expects fund redemptions to continue generating opportunities to acquire real estate from owners seeking liquidity, while higher interest rates are likely to put further pressure on smaller, highly leveraged companies.
For Realty Income, he said, the combination of scale, capital access and market fragmentation should continue to create opportunities. “All of the reasons why we entered here continue to be playing out the way we said,” Roy said.
To read the latest IPE Real Assets magazine click here.