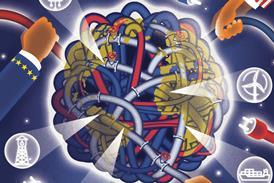
Democrat success in the midterm elections has given AI infrastructure investors cause for concern. Christopher Walker looks at the new outlook for the sector
While a Democrat ‘blue wave’ was expected in the midterms last week, a ‘blue tsunami’ was not. Wall Street raced to reprice the risk of data-centre operators – Applied Digital fell 8.8%, CoreWeave 9.5% and Cipher Digital 21% – seemingly under the assumption that Democrats would seek more regulation and potentially constrain America’s AI boom.
So where does this really leave investors that have allocated substantial capital to the buildout of AI infrastructure in the US? The concern is understandable, especially as it coincides with growing public opposition to the construction of large facilities in communities across the US. Leftist senator Bernie Sanders has demanded a “national data-centre moratorium”, arguing that “Americans don’t want Big Tech oligarchs wrecking the environment”.
Most commentators agree that the long-term prospects for data centre investment will remain strong due the huge demand-supply imbalance, but there is potential for some disruption along the way, and this has to do with changing dynamics around decision-making and power.
“This is purely a timing issue and by no means structural,” says Mehdi Paryavi, CEO of the International Data Center Authority. “Democrats are not fundamentally against data centres. Everyone on both sides of the aisles knows that data centres are the future infrastructure of the country and historically they have spent more in critical infrastructure than their political opponents.”
But it is likely that there will be “temporary but necessary slowdowns”, he admits – that is, “until a few key matters are solved, or at least conceptualised – such as overall control over AI, and, of course, the immense shortage of resources, including energy and human capital”.
Jon Phillips, chief executive of the Global Infrastructure Investor Association, paints a similar picture. “These elections do not change America’s requirement for AI infrastructure, but they do change who sets the terms. “Decisions on data centres are moving to the states. The risk now is a fragmented federal, state and local framework that alters project economics after capital has been committed.”
In Texas, which previously a Republican stronghold and the very epicentre of the date-centre boom, Democrat governor-elect Gina Hinojosa has promised “a ban on all data-centre approvals until laws can be passed by the legislature to protect Texans”. Ohio’s Amy Acton and Georgia’s Keisha Lance Bottoms campaigned on similar restrictions.
The timing of the Democrat success coincides with changes in the risks relating to data-centre development, not least a recent rise in public opposition. Rich Hill, head of global real estate research at Principal Asset Management, says: “Data centres have moved from a largely local land-use issue to a broader political focus, combining voter angst over affordability and resource use with growing unease about AI itself.”
Situation seems to favour the incumbents
Existing data centres and those under construction look to be in the strongest position, while planned developments are looking more vulnerable.
Axel Drwenski, head of research and strategy for real assets at Helaba Invest, says his firm‘s “investment thesis remains unchanged” when it comes to data centres. But the situation now means that “not every project currently in the pipeline will ultimately be realised”, he adds. “A more restrictive regulatory environment, combined with a growing shortage of suitable sites, is likely to push costs higher. The sector’s ‘Wild West’ boom phase is gradually coming to an end.”
Hill adds: “Rather than stopping development altogether, the broader direction is more likely to be toward changing the terms under which it proceeds. Authorities are likely to demand more from developers. That could mean greater responsibility for grid and infrastructure costs, protections for households from higher electricity bills, enhanced disclosure of energy and water consumption, closer scrutiny of tax incentives, and more explicit investment in surrounding communities.” Getting there could be “disruptive”.
Existing data centre incumbents with established footholds, could benefit from less competition from newly-built data centres. “We saw a similar dynamic in other areas of energy infrastructure,” says Jags Walia, head of global listed infrastructure at Van Lanschot Kempen, pointing to when the US administration under Joe Biden placed restrictions on approvals for new liquefied natural gas export facilities. “When it becomes more difficult to bring new infrastructure online, assets that are already operational become more valuable.”
Drwenski therefore expects to see a “further concentration of data centres in already established locations”. He also predicts “an additional boost to resource-efficient technologies – a form of environmental protection through the back door, so to speak”.
The situation also potentially puts utilities in a stronger position. Walia talks of “an important shift in bargaining power that regulation will bring”. He explains: “If developers are required to identify and secure an electricity supplier before obtaining planning approval, this strengthens the negotiating position of utilities relative to data centre operators.”
Paryavi is optimistic about opportunities. “The data centre industry is one of the most innovative and forward-thinking industries; however, there are still high levels of under utilisation in servers, storage, networks and even power and cooling systems all over the country,” he says.
“In the long run, we don’t foresee any problems. Higher costs of data centres will result in higher costs of compute and thus higher costs of digital applications and services that even the data centre opposition is using on day-to-day basis. Eventually, the market will either accept to pay the higher rates or ease down on the very infrastructure that supports their modern way of life.”